Regulation
What Are Singapore's TP Documentation Requirements?
CA Mithilesh Reddy
13 Sept 2026 · 12 min read
Direct answer
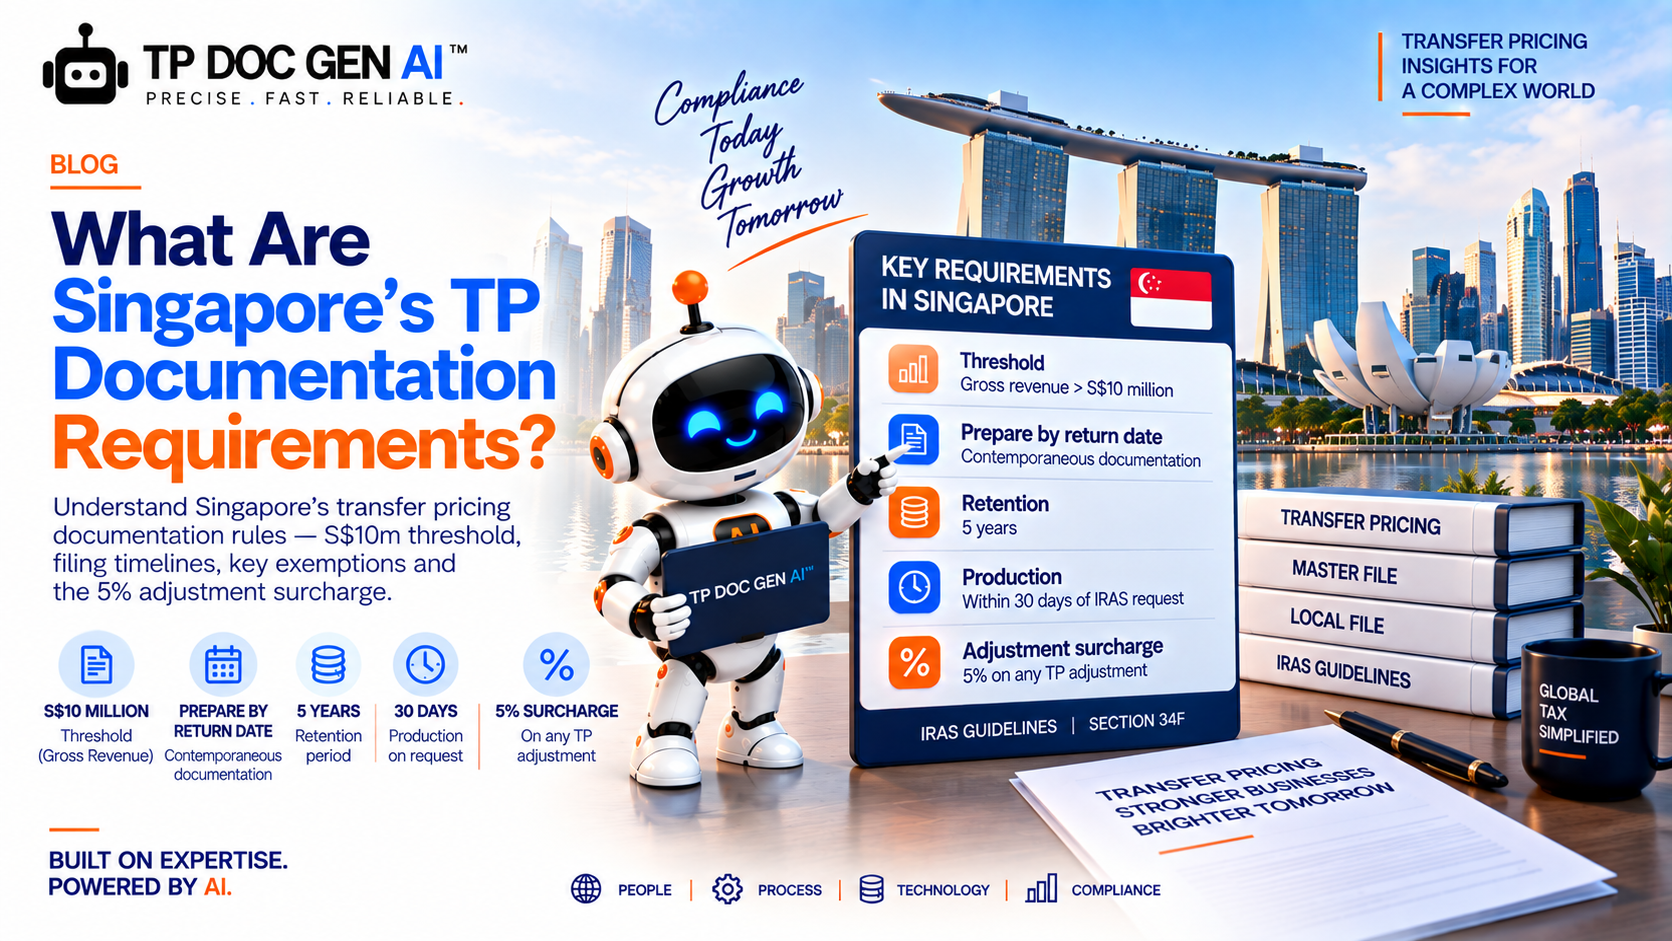
Singapore requires contemporaneous transfer pricing documentation under Section 34F of the Income Tax Act 1947 where gross revenue exceeds S$10 million for the basis period (or documentation was required for the previous one). The file must be prepared by the return filing date, retained for five years, and submitted within 30 days of an IRAS request - against the backdrop of a 5% surcharge on any transfer pricing adjustment. The underlying framework can be reviewed in the Transfer Pricing.
Why this question matters
What Are Singapore's TP Documentation Requirements? is not only a definition or filing question. It affects how a multinational group captures transactions, allocates responsibility, prepares financial data and responds when a tax authority asks for evidence. The key professional issue is the current IRAS guidance, S$10 million trigger, transaction exemptions, contemporaneous timing, 30-day production and 5% adjustment surcharge. A technically correct rule can still be applied badly when the facts, accounting records and documentation workflow are disconnected. For the official position, refer to IRAS e-Tax Guides.
The analysis in this article is framed for Singapore. OECD materials provide a common technical language, but local legislation, rules, forms and administrative guidance govern the legal obligation. Thresholds and deadlines are therefore presented with a verification date and should be reconfirmed before a filing or transaction decision. Additional authoritative context is available in Country-by-Country Reporting.
The rules in one table (as at August 2026)
| Element | Requirement |
|---|---|
| Trigger | Gross revenue > S$10m, or documentation required for the prior basis period |
| Content | Two-part file per the IRAS TP Guidelines (Ninth Edition, 2026): group-level and entity-level information - Master File and Local File in substance |
| Timing | Prepared by the tax return filing due date; dated |
| Retention | 5 years from the end of the basis period |
| Production | Within 30 days of IRAS request |
| Penalty | Fine up to S$10,000 per offence for documentation failures |
| Surcharge | 5% of any TP adjustment, payable even in loss positions |
The exemptions that lighten the load
Above the trigger, documentation is still not required for categories including: transactions covered by an APA (reduced file); domestic related-party transactions taxed at the same rate; related-party loans priced with IRAS's indicative margin (available for loans not exceeding S$15m); routine support services charged at the accepted 5% cost mark-up; and categories whose values fall under the per-category thresholds in the Guidelines. Singapore's design concentrates effort where pricing judgment actually operates. The underlying framework can be reviewed in the Corporate Income Tax.
What makes Singapore distinctive
- The surcharge changes loss-year incentives - 5% attaches to the adjustment itself, so weak files cost money even when no extra tax arises.
- Two genuine safe harbours - the indicative loan margin and the 5% services mark-up are among the cleanest administrative simplifications anywhere; use them where they fit.
- Guidelines that actually move - IRAS updates its TP Guidelines regularly; each year's file should be checked against the current edition rather than rolled forward on autopilot.
- Local-first comparables preference - regional sets are accepted with justification; document the search hierarchy explicitly.
FAQ
Is the S$10m test on group or entity revenue? The taxpayer's own gross revenue for the basis period - an entity-level test, unlike group-revenue triggers elsewhere. For the official position, refer to OECD Transfer Pricing Guidelines 2022.
Is there a separate disclosure form? Yes - the Related Party Transactions reporting with Form C applies above the RPT reporting threshold; it must reconcile with the Section 34F file. Additional authoritative context is available in BEPS Action 13: Transfer Pricing Documentation and CbCR.
Do dormant or loss-making companies need documentation? If the trigger is met, yes - and the surcharge applies to adjustments regardless of tax payable.
When can documentation be in simplified form? For qualifying categories under the Guidelines' exemptions and safe harbours; everything else takes the full two-part file, dated by the return deadline.
How should the issue be handled in practice?
Step 1: Confirm scope and timing
Determine the legal entity, fiscal period, transaction classes, thresholds, exemptions, preparation date, submission window and retention period under the current local rules. For Singapore transfer pricing documentation requirements, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved. The underlying framework can be reviewed in the Transfer Pricing Country Profiles.
Step 2: Create one transaction register
Reconcile related-party counterparties and values to the general ledger, statutory accounts, tax return and disclosure form. Record currency, agreement, method, counterparty and owner for every material flow. For Singapore transfer pricing documentation requirements, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Step 3: Capture the business facts
Prepare the entity and industry overview, conduct interviews and document functions, assets, risks, business strategy, changes and exceptional events. The file should describe the year under review, not last year's structure. For Singapore transfer pricing documentation requirements, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Step 4: Complete the economic work
Select the method, tested party and PLI where relevant; run the comparable analysis; preserve the search trail; and reconcile the result to the entity's accounts. For Singapore transfer pricing documentation requirements, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Step 5: Review, approve and archive
Run legal, numerical and consistency reviews. Preserve the signed or filed version, database evidence, calculations, approvals and submission acknowledgements in one indexed evidence pack. For Singapore transfer pricing documentation requirements, record unresolved assumptions and the person responsible for confirming them before the conclusion is approved.
Worked example
A Singapore company exceeds the revenue trigger but assumes the overseas group's policy file is sufficient. The group document does not explain the Singapore entity's functions, transactions or financial results. The local company must supplement it so the Section 34F content and arm's length position can be tested. For the official position, refer to UN Practical Manual on Transfer Pricing 2021.
The example does not establish a universal answer. It shows why the sequence matters: define scope, establish conduct, apply the local rule, perform the economic analysis, reconcile the figures and document the review. If one of those links changes, the conclusion may also change.
What will a senior transfer-pricing reviewer challenge?
A Local File is tested as an integrated record. Entity narrative, transaction schedule, FAR, method, benchmarking and financial outcome should describe the same arrangement. Completeness of headings does not compensate for inconsistency between sections.
The most common review issue is a missing bridge between statutory accounts and the tested result. Segmental statements, allocation keys and excluded items should be transparent enough for an independent reviewer to reperform.
Contemporaneous preparation also requires version discipline. Preserve the sources and calculations that existed by the relevant preparation date, then separately document later audit updates rather than rewriting history.
Evidence and documentation checklist
- Scope memorandum: Entity, period, jurisdiction, transaction or obligation, threshold test and exclusions, with the current legal source recorded.
- Legal and ownership records: Entity chart, related-party analysis, permanent-establishment mapping and relevant registrations or taxpayer classifications.
- Executed agreements: Contracts, amendments, pricing schedules, service descriptions, licence terms, financing terms and evidence that conduct followed the agreed framework.
- Transaction register: Counterparty, amount, currency, invoice or journal source, method, owner and reconciliation status for each controlled flow.
- Functional evidence: Interview notes, organisation charts, approval matrices and documents showing who performed functions, used assets and controlled risks.
- Economic workpapers: Method memorandum, database query, filters, comparable accept-reject matrix, adjustments, PLI or valuation calculations and range.
- Financial bridge: Reconciliation from audited or reliable accounts to transaction values, segmental results, operating classifications and the tested outcome.
- Cross-report consistency check: Comparison with the tax return, disclosure form, Local File, Master File, CbCR and counterparty treatment, with differences explained.
- Review and approvals: Preparer, reviewer, unresolved assumptions, resolution evidence, sign-off date and the exact version approved for filing or submission.
- Filing and retention evidence: Submission acknowledgement, correspondence, authority requests, response index and a retention period aligned with local law.
Common failure patterns
- Treating Singapore transfer pricing documentation requirements as a wording exercise instead of linking the conclusion to contracts, conduct and accounts.
- Using a global policy without documenting the local legal overlay, threshold, form, deadline or language requirement.
- Rolling forward the previous year without testing changes in entities, transactions, people functions, risks, markets and accounting classifications.
- Presenting precise calculations without preserving source data, screening decisions, assumptions and a financial reconciliation.
- Allowing the Local File, disclosure form, return, Master File, CbCR or counterparty documentation to use different transaction populations without an explanation.
- Treating AI-generated drafting as professional approval, or making absolute product claims that are not supported by the facts and controls.
How TP DOC GEN AI can support this work
TP DOC GEN AI can assemble entity data, related-party transactions, FAR narratives, economic analysis, annexures and source-controlled drafting in one workspace. This reduces re-keying and inconsistency risk while keeping human review and sign-off explicit. Local Files and Master Files remain professional deliverables that must be checked against the applicable law and actual conduct.
Relevant product page: See the TP DOC GEN AI workflow. The most useful demonstration is an anonymised scenario that mirrors the entity, transaction and jurisdiction your team actually handles.
Next step: Book a personalised demo and ask the specialist to show the source trail, calculation controls, reviewer workflow and final Word/PDF output.
Additional questions professionals frequently ask
Is a benchmarking report enough?
Usually not. It may support the economic analysis but does not replace entity information, transaction descriptions, agreements, FAR and financial reconciliation required in a full Local File.
When should preparation begin?
During the transaction and financial-close cycle. Waiting for a request compresses fact gathering, analysis and review into the authority's production window.
Can last year's file be rolled forward?
Only after a documented change assessment covering entity facts, transactions, contracts, people functions, risks, financial definitions and comparables.
What should be retained with the final file?
The exact report, source documents, database exports, screening matrix, PLI and range calculations, financial bridge, approvals and any filing or submission acknowledgement.
What is the first practical step for Singapore transfer pricing documentation requirements?
Define the exact entity, transaction or obligation and governed period. Then identify the official rule, responsible business owner, required source records and deadline. Starting with a template before scope is settled usually creates rework and hides omissions.
How should a multinational group govern Singapore transfer pricing documentation requirements?
Use a group framework for definitions, data and review, but document local overlays for Singapore. Maintain one approved transaction population, a jurisdiction-specific obligation register and a controlled process for exceptions.
Where should professional judgement be recorded?
In the working papers and final narrative wherever facts are interpreted, alternatives are rejected, comparability adjustments are made or a legal threshold is applied. The record should identify the evidence, reasoning, reviewer and date.
How can the content remain useful after publication?
Show the last-verified date, link directly to official authorities, avoid absolute claims that depend on facts and schedule a periodic regulatory review. This also improves trust for search engines and answer engines.
Practitioner's implementation notes
From a finance-function perspective, Singapore transfer pricing documentation requirements should not sit in a tax-only folder. The underlying transaction originates in contracts, operating decisions and accounting systems. Tax can analyse the position only when legal, finance and business owners provide a common description and agree how the numbers are extracted.
For Singapore, the official source should be retained with an access or verification date because webpages, forms and administrative guidance can change. When the law changes, update the current-year workpaper while preserving the source used for an earlier filing. Version control is part of technical accuracy.
AEO and GEO visibility depend on answer quality, not merely question-shaped headings. Each answer should be self-contained, identify the jurisdiction and period, distinguish a general principle from a filing rule, and link to the primary authority. This makes the page easier for professionals, search engines and AI answer systems to interpret.
The practical standard for Singapore transfer pricing documentation requirements is reproducibility. A reviewer who was not involved in preparation should be able to locate the source facts, understand the judgement, reperform the material calculation and identify the final approved output without relying on the original preparer's memory.
Management information should also track exceptions: transactions without agreements, entities with changed functions, missing segmental accounts, unreconciled disclosure values, stale comparable searches and deadlines without an owner. An exception register converts a long report into an operating control.
Finally, materiality should guide effort but should not be confused with legal scope. A low-value item may require disclosure even when extensive benchmarking is disproportionate, while a high-value recurring flow may justify deeper analysis, bilateral certainty or more frequent monitoring. Record both the legal requirement and the risk-based response.
Conclusion
A defensible position on Singapore transfer pricing documentation requirements combines current law, verified facts, reliable analysis, reconciled financial information and an accountable review trail. The goal is not simply to produce a long document. It is to create a record that another professional can understand, reperform and defend after the people and systems involved have changed. Additional authoritative context is available in Toolkit for Transfer Pricing Documentation Requirements.
Editorial and professional disclaimer
This article provides general educational information and is not tax, legal, accounting or investment advice. Transfer-pricing outcomes depend on the applicable law, tax year, jurisdiction and facts. Qualified advisers should be consulted before filing or adopting a position.
More on Regulation
Regulation 13 Sept 2026 16 min read
UAE Free Zone Transfer Pricing: QFZP Guide
Learn how transfer pricing affects UAE Qualifying Free Zone Persons, qualifying income, de minimis limits, substance, documentation and controls.
Regulation 13 Sept 2026 15 min read
Connected Persons under UAE Corporate Tax: Article 36
Understand UAE connected-person rules, Article 36 deductions, market value, business purpose, disclosure and practical documentation controls.
Regulation 13 Sept 2026 16 min read
India Safe Harbour Rules 2026: Rates vs APA
Understand India’s transfer pricing safe harbour rates, eligibility, compliance steps and when an APA may provide better long-term certainty.